

News
The Super Mansion Market in 2026


Records, Bunkers and a Widening Gap at the Very Top
The super mansion market — that narrow, rarefied slice of ultra-luxury real estate where prices run into the tens and hundreds of millions — has not just continued growing through 2026, it has become one of the most extreme expressions yet of the widening gap between the world’s wealthiest buyers and everyone else. What was already an exclusive niche a year ago has fragmented further into distinct sub-markets: trophy homes bought for status and visibility, and a newer, quieter category of ultra-secure compounds built specifically to disappear.
A Record-Breaking Year for the Very Top of the Market
The scale of 2025’s ultra-luxury activity set the stage for an even more concentrated 2026. All ten of the most expensive home transactions in the United States in 2025 exceeded $100 million, up from just five in each of 2023 and 2024 — a shift dramatic enough that the Wall Street Journal dubbed 2025 “the year of the $100 million house.” Globally, more than 2,100 ultra-luxury homes priced above $10 million changed hands over the twelve months through late 2025, according to Knight Frank. That momentum has carried directly into 2026: a Bel-Air megamansion listed this year at $400 million to become the most expensive home currently on the market in the US, alongside a $300 million Aspen estate and a $237 million Key Biscayne waterfront property — any one of which, if it closes near asking price, would shatter the current US sale record of roughly $238–240 million, set by a Manhattan penthouse in 2019.
Generational wealth transfer is doing much of the heavy lifting behind this demand. Sotheby’s International Realty’s 2026 Luxury Outlook report puts the value of inherited wealth transferred in 2025 alone at roughly $6 trillion — about 10 percent of global GDP — with much of that capital flowing directly into luxury real estate as both a lifestyle purchase and a wealth-preservation vehicle. Sotheby’s own global sales volume reflects the trend: $182.4 billion in 2025, up 16 percent year-over-year, alongside a 44 percent surge in foreign buyer activity in the US.
Where the Money Is Moving
The geography of ultra-luxury demand has shifted meaningfully since 2025. Miami has overtaken both New York and the Bay Area in ultra-luxury sales volume in 2026, driven by continued wealth migration to low-tax states — the city has recorded more $30 million-plus home sales than New York in the first half of the year, while New York logged just 17 such deals over the same period, a slowdown brokers link partly to a newly effective pied-à-terre tax that has prompted some luxury buyers to pause. Dubai remains arguably the world’s most dynamic ultra-luxury market in 2026, with Palm Jumeirah and Emirates Hills properties appreciating 12 to 18 percent in 2025 alone, powered by zero income tax, a residency-by-investment program and world-class infrastructure that together function as a self-reinforcing magnet for global capital. Manhattan’s trophy segment — properties above $10 million — has itself rebounded, with transaction volume rising 11 percent in 2025 after two weaker years, even as buyers there increasingly weigh the city’s graduated mansion tax, which now runs as high as 3.9 percent on purchases above $25 million.
The New Frontier: Building to Disappear
Perhaps the most significant shift in the super mansion market since 2025 is not about price at all — it is about visibility. A growing cohort of the world’s wealthiest buyers, concentrated heavily among tech billionaires, is now investing in what LinkedIn co-founder Reid Hoffman has described as “apocalypse insurance”: secondary properties held in reserve rather than lived in, often in deliberately remote locations, with New Zealand emerging as the most sought-after destination for this particular category of buyer. The most extreme documented example is Mark Zuckerberg’s roughly $300 million, 567-acre compound under construction on the Hawaiian island of Kauai — a project planning documents describe as including more than 4,500 square meters of underground living space, blast-resistant doors, independent energy production and a dedicated water system, despite Zuckerberg’s own characterization of the project as simply “a little shelter.” This trend runs in parallel with, and reinforces, the broader “stealth wealth” shift reshaping mainland luxury buying more generally, where privacy trusts and off-market “whisper” listings are increasingly preferred over the publicized mega-sales that once defined the category.

What’s Fueling Demand
The drivers behind 2025’s boom remain firmly in place, with some new dimensions added in 2026:
- Billionaires and celebrities continue to anchor headline transactions, though increasingly through structures designed to obscure rather than publicize the buyer’s identity — a marked change from the splashy, press-released sales that defined the category as recently as 2019.
- Institutional and family office capital continues treating ultra-luxury real estate as a genuine portfolio diversifier and inflation hedge, a thesis reinforced in 2026 by the sheer scale of the generational wealth transfer now underway.
- Wellness and longevity have emerged as a distinct new demand driver this year: Sotheby’s mid-2026 outlook reports that wellness-oriented real estate has more than doubled in size over five years and is projected to surpass $1.1 trillion by 2029, with nearly 38 percent of agents working the $10 million-plus segment reporting client interest specifically in longevity-oriented amenities.
- Security and self-sufficiency, as the Zuckerberg compound illustrates, have moved from a luxury feature to, for a meaningful subset of buyers, the primary purpose of the purchase itself.
Persistent Challenges
The obstacles facing the category in 2025 have largely carried into 2026, with some sharpening. Financing costs remain elevated for buyers who do lever their purchases, even though the prime segment is increasingly insulated by the prevalence of all-cash transactions. Inventory in the most sought-after addresses — Manhattan’s Billionaires’ Row, Dubai’s Palm Jumeirah, London’s Mayfair — remains structurally scarce, a scarcity that continues to support pricing even as broader housing markets soften. And the market’s extreme exclusivity continues to mean a genuinely thin buyer pool and long, unpredictable sales timelines for anything priced above roughly $100 million, regardless of how much aggregate wealth is chasing the category.
The Bottom Line
The super mansion market in 2026 is not simply larger than it was in 2025 — it has become more stratified, more private, and in the case of the emerging bunker-compound category, more explicitly about resilience than lifestyle. For elite investors and family offices, the category continues to offer genuine wealth-preservation characteristics, but the calculus has shifted: the highest-profile, most publicized trophy sales are increasingly a smaller share of total ultra-luxury activity, with a growing portion of capital instead flowing into precisely the kind of off-market, security-focused, deliberately invisible real estate that generates no headlines at all.
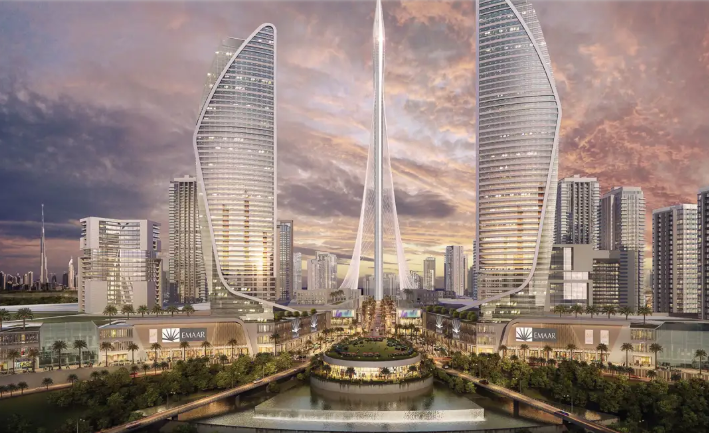
Investing in the World’s Tallest Buildings: The 2026 Playbook for Supertall Real Estate
Real estate tied to the world’s tallest buildings continues to sit in a category of its own. These towers are not simply large buildings — they are engineered scarcity, occupying irreplaceable positions in global financial hubs, commanding tenant and buyer premiums that ordinary Grade-A stock cannot match, and generating income from far more than rent alone. As of September 2026, the five tallest completed buildings on Earth, ranked by the Council on Tall Buildings and Urban Habitat, are Burj Khalifa in Dubai, Merdeka 118 in Kuala Lumpur, Shanghai Tower, the Makkah Royal Clock Tower in Saudi Arabia, and the Ping An Finance Centre in Shenzhen. Together they offer a useful cross-section of how supertall real estate actually performs as an investment class — and where the risks sit.
Burj Khalifa, Dubai, UAE — 828 meters, 163 floors
Burj Khalifa has held the title of world’s tallest building since 2010 and, at 828 meters, still leads its nearest rival by close to 150 meters — a margin that has remained essentially unchallenged for fifteen years. Developed by Emaar Properties, the tower is a mixed-use asset combining luxury residences, corporate offices, the Armani Hotel and extensive retail, with residential units historically transacting at premium pricing in Dubai’s ultra-prime segment. The investment case rests less on any single income line than on the combination: residential sales and rentals, office leasing, hotel operations, and one of the highest-grossing observation decks in the world, all under one address whose brand value alone commands a premium over otherwise comparable Downtown Dubai product. Emaar itself remains one of the most closely watched developers globally — the company’s chairman confirmed this year that Dubai hotel occupancy has recovered to around 60 percent after dipping sharply during regional conflict, and Emaar is preparing a roughly $55 billion urban development for once conditions stabilize further, underscoring the scale of capital still committed to the emirate’s built environment.
Merdeka 118, Kuala Lumpur, Malaysia — 678.9 meters, 118 floors
Completed in 2023 and developed by state-linked investment fund Permodalan Nasional Berhad, Merdeka 118 is the world’s second-tallest building and the tallest in Southeast Asia. The tower combines offices, a Park Hyatt hotel, retail and residential space in Kuala Lumpur’s financial district, and its sustainability credentials — energy-efficient systems designed to meet international green-building standards — have made it a reference point for ESG-oriented institutional capital looking at Southeast Asian office exposure. For multinational tenants seeking a single prestige address in Kuala Lumpur, Merdeka 118 functions similarly to how Petronas Towers did a generation earlier: an anchor asset whose scarcity value supports premium rents even as broader Kuala Lumpur office stock faces more competitive, oversupplied conditions.
Shanghai Tower, Shanghai, China — 632 meters, 128 floors
Shanghai Tower, the world’s tallest twisting skyscraper, anchors Shanghai’s Lujiazui financial district alongside the Shanghai World Financial Center and Jin Mao Tower, forming one of the most concentrated clusters of supertall office space anywhere on Earth. Owned and operated by Shanghai Tower Construction & Development, the building combines Grade-A offices, a Jin Jiang-operated luxury hotel, retail and one of the world’s highest observation decks. Its investment profile is distinct from the Gulf and Southeast Asian towers on this list in one important respect: as a state-linked asset in a market where foreign direct ownership of trophy office towers is tightly controlled, exposure for international investors typically comes indirectly, through listed developers, REIT-like vehicles, or joint-venture leasing arrangements with multinational tenants, rather than through direct equity ownership of the tower itself.
Makkah Royal Clock Tower, Mecca, Saudi Arabia — 601 meters, 120 floors
The Makkah Royal Clock Tower is the tallest hotel building in the world and the anchor of the Abraj Al-Bait complex overlooking the Masjid al-Haram, the holiest site in Islam. Its investment profile is unlike any other building on this list: demand is driven not by corporate tenancy or luxury residential appeal but by religious pilgrimage, with the Hajj and Umrah seasons generating extraordinarily high and highly predictable occupancy for the Fairmont-operated hotel component. Saudi Arabia’s broader push to expand religious tourism capacity — alongside the kingdom’s parallel real estate opening measures, including its newly operational foreign property ownership framework and the Public Investment Fund’s coastal development pipeline — makes Mecca’s hospitality-anchored supertall real estate one of the more insulated income profiles in this category, largely uncorrelated with the global office and luxury residential cycles that drive the other towers on this list.
Ping An Finance Centre, Shenzhen, China — 599.1 meters, 115 floors
Built as the headquarters for Ping An Insurance, China’s second-largest insurer, the Ping An Finance Centre anchors Shenzhen’s Futian central business district and is directly integrated with the city’s metro network and the Guangzhou–Shenzhen–Hong Kong high-speed rail link — a degree of transit integration that is itself a meaningful driver of long-term tenant demand in a city that has grown to nearly 13 million people since its designation as a Special Economic Zone. More than 100 floors of office space, occupied principally by Ping An and its financial-services subsidiaries, sit above a retail podium and conference facilities, with a public observation deck and private club occupying the pyramidal crown. As with Shanghai Tower, direct foreign equity access is limited; the more realistic route for outside investors is indirect, through listed Chinese financial and property vehicles or leasing relationships, rather than acquiring a stake in the tower itself.
Why Supertall Real Estate Behaves Differently From Ordinary Prime Assets
Several structural features distinguish these buildings from conventional trophy office or residential towers, and they explain why supertall assets have historically commanded a premium even through real estate downturns. First is brand value: a Burj Khalifa or Merdeka 118 address functions as a marketing asset in its own right for corporate tenants and luxury buyers, which supports occupancy and pricing power independent of local market softness. Second is revenue diversification — nearly every building on this list blends office, hospitality, residential and tourism income streams under a single roof, which cushions the asset against a downturn in any single sector in a way a pure-play office tower cannot replicate. Third, and increasingly relevant to ESG-focused institutional capital, is sustainability positioning: newer entrants to the supertall category, Merdeka 118 chief among them, have been designed from the outset to meet international green-building certification standards, a factor that is becoming a genuine underwriting criterion rather than a marketing footnote for large allocators.
The Access Problem — and Where Tokenization Genuinely Fits
The single biggest constraint on investing in this category is access. These are, almost without exception, either sovereign-linked, state-owned or closely held corporate assets, meaning direct equity ownership is simply not available to most investors, institutional or individual. That access gap is precisely why real estate tokenization has drawn serious institutional attention over the past two years — not as a retail gimmick, but as a genuine mechanism for fractionalizing ownership of otherwise inaccessible trophy assets. Dubai’s Land Department, working with the Virtual Assets Regulatory Authority and the Central Bank of the UAE, has already launched a pilot phase of blockchain-based real estate tokenization specifically framed around expanding fractional ownership and international participation in the emirate’s property market. Academic and regulatory frameworks published this year have likewise moved tokenization from experimental blockchain use case toward regulated market infrastructure, emphasizing that the technology is best understood as augmenting existing ownership and regulatory structures rather than replacing them.
For investors specifically interested in supertall and trophy real estate, the realistic paths to exposure today remain listed developer equity — Emaar Properties for Dubai exposure, PNB-linked vehicles for Merdeka 118, listed Chinese property and insurance names for Shanghai Tower and Ping An Finance Centre — alongside REITs holding comparable trophy assets, and a still-nascent but regulator-backed tokenization market that is worth monitoring closely rather than entering on the basis of any single platform’s marketing claims. As with any emerging asset-access mechanism, the platforms offering fractional or tokenized exposure vary enormously in regulatory standing, custody arrangements and transparency, and warrant the same due diligence an investor would apply to any unlisted vehicle — verified regulatory registration, clear custody of the underlying asset, and an audited link between the token and actual title or economic rights, rather than marketing promises of low minimums and instant liquidity.
The Bottom Line
Supertall buildings remain among the most resilient trophy assets in global real estate precisely because so little new competing supply can realistically be built — each of the towers above required years of specialized engineering, extraordinary capital outlay and, in several cases, direct government or sovereign backing to complete. That scarcity is the entire investment thesis. The risk for investors is less about the buildings themselves and more about the access route chosen to reach them: direct ownership is largely closed, indirect listed exposure carries the operating and governance risk of the parent developer or state entity, and the tokenization route, while increasingly credible where regulators like Dubai’s are directly involved, still requires far more scrutiny of the platform than of the underlying asset.
News
Private Real Estate’s Elite Managers Raised $223 Billion for Core Strategies — What the New PERE Core 100 Reveals
For the first time, PEI Group’s PERE has published a dedicated ranking of the world’s leading core and core-plus real estate managers — the PERE Core 100 — and the inaugural results show that the 100 leading private real estate managers raised a combined $223.24 billion for core and core-plus strategies between 2021 and 2025. The creation of a standalone ranking is itself significant: core and core-plus capital had previously been explicitly excluded from PERE’s flagship PERE 100 ranking of opportunistic and value-add managers, meaning this is the first time the scale of institutional capital flowing specifically into lower-risk, income-generating real estate strategies has been measured and made visible as its own distinct market.
That distinction matters more than it might first appear. Core and core-plus strategies target stabilized, well-located, income-producing assets with modest leverage and a focus on durable cash flow rather than value creation through development, repositioning or distressed acquisition — the institutional equivalent of a defensive, lower-volatility allocation within real estate itself. The fact that this segment alone commands $223 billion in five-year fundraising, tracked separately from the opportunistic and value-add capital chronicled in the main PERE 100 ranking, underscores how large and how institutionally embedded the demand for lower-risk real estate income has become, particularly among pension funds, insurance companies and sovereign wealth vehicles that need durable, predictable cash flow to match long-duration liabilities.
The broader fundraising backdrop gives useful context for interpreting that figure. The main PERE 100 ranking — covering opportunistic and value-add strategies — saw its aggregate five-year fundraising total grow for the first time since 2023 this year, adding roughly $52 billion to reach a new high after a two-year, 10 percent decline in magnitude from a 2023 peak of $722.2 billion. Notably, more than half of that renewed growth came not from the longtime fundraising leaders Blackstone and Brookfield, but from Blue Owl Capital and Ares Management, which together added $29.5 billion — enough for Blue Owl to displace Brookfield from second place in the ranking for the first time since 2018, and for Ares to jump from tenth to fourth place in a single year. Read alongside the new Core 100 data, the picture that emerges is of a private real estate capital-raising market bifurcating along risk lines: a reviving, increasingly concentrated opportunistic and value-add segment where a small number of scaled managers are pulling further ahead, running in parallel with a now-separately-tracked, similarly massive core and core-plus segment serving investors who want real estate exposure without the volatility.
What this bifurcation reveals about where institutional capital believes real estate is headed is instructive for anyone allocating into the asset class. The willingness of $223 billion in core and core-plus capital to flow into stabilized, income-generating real estate over a period that included significant repricing, rate volatility and sector-specific stress — particularly in offices — suggests institutional investors have not lost confidence in real estate as an asset class broadly, but have become considerably more discriminating about which risk profile within real estate they are willing to underwrite. Core capital wants certainty of income; it is flowing toward logistics, multifamily and select retail and alternative sectors with durable occupier demand, not toward the speculative development or distressed-asset strategies that dominated opportunistic fundraising in prior cycles.
For real estate managers themselves, the emergence of a standalone Core 100 ranking is also a competitive signal. Firms that have historically been known as opportunistic or value-add specialists — the Blackstones and Brookfields of the world — are increasingly being measured against a parallel universe of managers who compete purely on their ability to source, underwrite and manage stabilized income-producing assets at scale. As pension funds and insurers continue to grow their allocations to real estate as a source of inflation-linked, long-duration income, the managers who can demonstrate scaled, disciplined core capabilities — not just opportunistic deal-making prowess — may find themselves increasingly well positioned to capture the next wave of institutional capital, regardless of where the broader real estate cycle heads from here.
Stealth Wealth Is Rewriting the Rules of Luxury Real Estate — And Reshaping How the Ultra-Rich Transact
For most of the past century, the ultra-wealthy wanted their real estate purchases to be seen. A splashy listing, a glossy press release, a named buyer attached to a record-breaking sale — all of it served as a public signal of arrival and status. That era is ending. A growing class of ultra-wealthy buyers, according to reporting from Fortune, is now deliberately routing home purchases through limited liability companies, privacy trusts and so-called “whisper” listings that never touch the multiple listing service, in a shift the industry has come to call stealth wealth buying. The goal is no longer to maximize price through public exposure — it is to disappear from the public record entirely.
Ken DeLeon, founder of Palo Alto-based DeLeon Realty and one of Silicon Valley’s most prolific luxury brokers, dates the beginning of the shift to roughly three years ago, coinciding with a fresh wave of wealth creation tied to artificial intelligence. As he explained it, increased wealth has brought about greater security concerns and a stronger desire for privacy, with AI-driven wealth creation in Silicon Valley amplifying both. That combination — extraordinary and rapid new wealth, concentrated in a small number of highly visible technology executives, arriving during a period when AI itself has become an intensely scrutinized and sometimes controversial subject — has created a buyer class with every incentive to keep both their addresses and their net worth out of public databases.
The mechanics of a stealth wealth transaction go well beyond simply buying through an LLC. According to DeLeon, brokers now function as buffers throughout the entire process, and privacy extends to nearly every downstream interaction tied to the home — utilities, deliveries, even packages for a client’s children are frequently registered under the LLC or trust name rather than the buyer’s personal identity, specifically so that no thread of public data can be traced back to the owner. This is privacy engineered not just at the point of sale, but sustained indefinitely through the ownership period.
The trend is not confined to Silicon Valley. Off-market residential sales have surged by at least 30 percent year-over-year across Brooklyn, Manhattan and Queens between 2024 and 2025, with Brooklyn alone accounting for roughly $5.4 billion in privately marketed transactions, according to data reported by The Real Deal. That scale suggests stealth wealth buying has moved from a tech-hub curiosity to a broader structural shift across the country’s most expensive residential markets.
The trade-off, however, is real and quantifiable. A February 2025 Zillow Research analysis of 2.7 million home sales found that properties sold off the MLS in 2023 and 2024 typically transacted for almost $5,000 less than comparable homes listed publicly — a median gap of roughly 1.5 percent, which in aggregate cost American sellers more than $1 billion in lost proceeds. In California specifically, that gap widened to 3.7 percent, or roughly $30,000 per home. DeLeon himself is candid that studies have consistently shown off-market listings across nearly all price points tend to sell for less than they would with full market exposure. For a growing subset of ultra-wealthy sellers, though, that discount is simply the going rate for anonymity — and DeLeon suggests the pendulum could eventually swing back toward full exposure once sellers fully internalize the price of privacy, though there is no sign of that reversal yet. For now, the direction of travel in the world’s most expensive residential markets is unmistakable: less visibility, more structure, and a growing premium placed on simply not being found.


The Super Mansion Market in 2026

The Best Real Estate Business Models for the Elite in 2026

Investing in the World’s Tallest Buildings

Maldives: Eagle Hills Advances a $12 Billion Waterfront and Marina Vision
Investing in the World’s Tallest Buildings
