

RealTechs
Top 10 Global Real Estate Investment Destinations for 2026

-
hese 10 countries stand out in 2026 for their combination of ROI, stability, lifestyle, and legal frameworks favorable to foreign investors. Here’s an in-depth look at each:
1. Mexico 🇲🇽 – Estimated ROI: 8%–13%
Recommended Areas: Tulum, Playa del Carmen, CancúnMexico stands out for its blend of natural beauty, low cost of living, and high profitability. Tulum and Playa del Carmen are world-class destinations with white sand beaches, cenotes, and Mayan ruins, attracting thousands of tourists and digital nomads monthly. Cancún, with its international airport and luxury resorts, draws global tourism. The Riviera Maya offers a balance of pristine nature and modern amenities. Continuous infrastructure improvements like the Tren Maya boost its appeal further. Properties appreciate quickly, and Airbnb yields high annual occupancy. Legal trusts (fideicomisos) ensure safe purchases by foreigners. In many tourist areas, ROI exceeds 10%, making Mexico a gem both for living and generating income.
2. Portugal 🇵🇹 – Estimated ROI: 7%–10%
Recommended Areas: Algarve, Setúbal, PortoPortugal has moved up the ranking as one of the fastest-growing property markets in the world: home prices have climbed roughly 48% over the past five years, and the momentum has held into 2026. The Algarve features stunning beaches, top-tier golf courses, and charming fishing villages perfect for vacation rentals. Setúbal continues growing as a luxury second-home area, while Porto stays trendy thanks to its culture and wine scene. High safety, a moderate cost of living, and steadily rising property values make Portugal a standout for both lifestyle and income — particularly for investors from Northern Europe and North America.
3. Costa Rica 🇨🇷 – Estimated ROI: 8%–12%
Recommended Areas: Tamarindo, Nosara, Guanacaste
Costa Rica is known for its political peace, economic stability, and environmental consciousness. Pacific beaches like Tamarindo and Nosara offer lush landscapes, world-class surfing, and a laid-back lifestyle. The eco-friendly approach attracts conscious investors and tourists looking for authentic experiences. No capital gains tax on real estate is a major advantage. Guanacaste combines natural beauty with high tourism demand and a growing expat and retiree community. Remote work is encouraged, and high-speed internet is available even in coastal zones. Buying is easy for foreigners, and the vacation rental market remains strong.
4. Dubai 🇦🇪 – Estimated ROI: 5%–8%
Recommended Areas: Downtown, Marina, JVC, Business BayDubai still blends luxury, safety, world-class infrastructure, and unique tax advantages — no income or real estate capital gains tax. It remains a global hub for business, tourism, and tech, attracting international talent and capital. Downtown and Marina areas feature futuristic architecture in high demand from tourists and executives alike, while JVC caters to a growing middle class seeking modern apartments. Yield expectations have moderated somewhat compared with the peak years: modern flats in districts like Business Bay and Jumeirah Village Circle now average 5%–7% rental returns, still supported by high occupancy and strong long-term rental demand.
5. Colombia 🇨🇴 – Estimated ROI: 8%–10%
Recommended Areas: Medellín, CartagenaColombia remains a top destination for high returns and low entry costs. Medellín has transformed into a modern, innovative city with eternal spring weather, great cuisine, and efficient transport. El Poblado is a favorite among digital nomads with coworking spaces, cafés, and nightlife. Cartagena offers Caribbean beaches and colonial history with strong international tourism. Foreign investment in property continues rising, and Airbnb activity is booming. Real estate is still very affordable, and urban renewal projects keep boosting downtown values.
6. Greece 🇬🇷 – Estimated ROI: 7%–10%
Recommended Areas: Athens, Crete, SantoriniGreece offers history, Mediterranean beauty, and Schengen zone access. Athens combines ancient charm with modern living, making it ideal for long-term and urban rentals. Islands like Crete and Santorini boast turquoise waters and whitewashed architecture, ranking among the most sought-after tourist spots in Europe. Seasonal rental demand is very high, and although property prices keep rising, they remain competitive. The Golden Visa program has attracted foreign investors since 2013, and Greece has stabilized its economy and upgraded tourism infrastructure.
7. Spain 🇪🇸 – Estimated ROI: 6%–9%
Recommended Areas: Málaga, Alicante, Costa del SolSpain offers a perfect climate, globally recognized beaches, and a top-tier transport network. Costa del Sol boasts over 300 days of sunshine per year, attracting European tourists and investors. Málaga is booming with new cultural, tech, and urban projects. Alicante blends traditional architecture, sea life, and affordability. Spain has clear property laws, and short-term rental demand keeps rising. Investor visas are available for non-EU citizens, and coastal areas retain value over time thanks to high tourist turnover.
8. United States 🇺🇸 – Estimated ROI: 7%–10%
Recommended Areas: Miami, Tampa, Austin, PhoenixThe U.S. remains one of the world’s most transparent and stable markets. Miami offers glamour, sun, and top Airbnb demand. Tampa and Phoenix are booming with population growth and affordability. Austin mixes tech, youth, and strong rental demand. Property laws favor landlords, and investors can use LLCs or trusts to purchase from abroad, with flexibility for long-term rentals, vacation rentals, or flipping.
9. Türkiye 🇹🇷 – Estimated ROI: 5%–7% (new entry)
Recommended Areas: Antalya, IstanbulTürkiye has climbed into the top tier of yield-driven markets through 2026. Seafront apartments in Antalya and Istanbul typically deliver around 6% yields, supported by growing domestic and foreign buyer interest. Relatively low entry prices compared to Western Europe, combined with strong tourism-driven short-term rental demand, make it an increasingly attractive pick for investors chasing cash flow rather than pure appreciation.
10. Georgia 🇬🇪 – Estimated ROI: 6%–7% (new entry)
Recommended Areas: TbilisiGeorgia has emerged as one of the standout rental-yield markets in the region. In Tbilisi, short-term rentals can generate up to 7% annually, driven by strong demand from tourists and remote workers. Low property costs, straightforward foreign-ownership rules, and a growing digital-nomad scene support the case for Tbilisi as an accessible, high-yield entry point.
Summary Table
Rank Country Recommended Areas Estimated ROI Key Benefits 1 Mexico 🇲🇽 Tulum, Playa del Carmen, Cancún 8%–13% Rapid appreciation, tourist demand, Airbnb-friendly, strong legal framework 2 Portugal 🇵🇹 Algarve, Setúbal, Porto 7%–10% Strong five-year price growth, tax-friendly, growing expat interest 3 Costa Rica 🇨🇷 Tamarindo, Nosara, Guanacaste 8%–12% Eco-lifestyle, tax advantages, growing digital nomad presence 4 Dubai 🇦🇪 Downtown, Marina, JVC, Business Bay 5%–8% No taxes, futuristic city, strong occupancy 5 Colombia 🇨🇴 Medellín, Cartagena 8%–10% Affordable, high demand, rising international profile 6 Greece 🇬🇷 Athens, Crete, Santorini 7%–10% Golden Visa, strong seasonal rental market 7 Spain 🇪🇸 Málaga, Alicante, Costa del Sol 6%–9% Sunshine, legal clarity, rising tourism 8 USA 🇺🇸 Miami, Tampa, Austin, Phoenix 7%–10% Transparent markets, legal security, flexible strategies 9 Türkiye 🇹🇷 Antalya, Istanbul 5%–7% Low entry cost, strong coastal rental yields 10 Georgia 🇬🇪 Tbilisi 6%–7% High short-term rental yields, easy foreign ownership Sources:
Immigrant Invest
Benoit Properties
Mirabello Consultancy
Estate Agent Power
Elite Luxury Real Estate
The next phase of property tokenization may depend less on blockchain experimentation and more on regulation, identity and legally recognized ownership
Real estate tokenization has spent years being presented as a technological revolution capable of fractionalizing property and opening traditionally illiquid assets to a broader investor base. A new systematic review published in September 2026 suggests that the more important question is increasingly institutional: how can tokenized real estate operate inside regulated markets while maintaining legally enforceable rights, identity controls, governance and secure transaction infrastructure?
The study, published in the Journal of King Saud University Computer and Information Sciences, reviewed 63 primary studies and examined real estate tokenization across architecture, ownership, transactions, certification, stakeholders, technology and adoption barriers. Its findings point toward a transition from registry-focused blockchain experiments toward marketplace-oriented models. But the authors emphasize that tokenization does not replace existing institutions. A digital token only has economic value when the underlying property right or investment claim is legally enforceable and recognized within the relevant regulatory framework.
This distinction is crucial for institutional investors. A blockchain can provide a technically reliable record, but the technology itself does not determine who legally owns a building. Real estate remains deeply connected to land registries, corporate structures, securities regulation, identity verification, taxation, valuation, custody and courts. The successful tokenized property market will therefore likely be one in which blockchain infrastructure becomes integrated with these institutions rather than attempting to bypass them.
Fractional ownership remains one of the most visible potential applications. Instead of requiring a single investor to acquire an entire building, an investment structure could theoretically divide economic interests into digital units. Investors could potentially obtain exposure to rental income or capital appreciation through smaller positions, while the underlying property remains held through an appropriate legal entity or structure.
But fractionalization is only the beginning. Institutional tokenization could eventually support more sophisticated functions: automated distributions, programmable compliance, digital transfer restrictions, transparent ownership records, faster settlement, improved audit trails and potentially more efficient secondary markets. The technological architecture becomes particularly interesting when multiple participants—investors, asset managers, registries, banks, custodians and regulators—can interact through interoperable systems.
The recent academic evidence also highlights the challenges. Identity assurance, legal enforceability, governance, privacy, interoperability, continuous security monitoring and long-term cryptographic resilience are among the requirements identified for regulated deployment. These are not secondary technical details. They are the infrastructure upon which institutional confidence depends.
For large investors, the real opportunity may therefore be less about buying a tokenized apartment and more about the financial infrastructure that tokenization could create around entire portfolios. Imagine a future in which thousands of properties can be represented digitally, ownership structures are machine-readable, compliance rules are embedded into transactions and investors can analyze portfolios through a standardized data layer.
That would transform tokenization from a retail-oriented novelty into an institutional operating system.
The market is not there yet. Much of the academic literature remains dominated by prototypes, simulations and conceptual frameworks, and legal structures vary significantly by jurisdiction. But the direction of research is becoming clearer. The central question is no longer whether a property can be represented digitally. It is whether the entire legal, financial and institutional ecosystem surrounding that property can become interoperable.
For Aurivance, that distinction is essential. The future of tokenized real estate will probably not be determined by the most spectacular blockchain demonstration. It will be determined by who can connect property rights, capital, compliance, identity, data and liquidity into a system investors can trust.
A PropTech platform is using artificial intelligence to compress weeks of early-stage property analysis into minutes
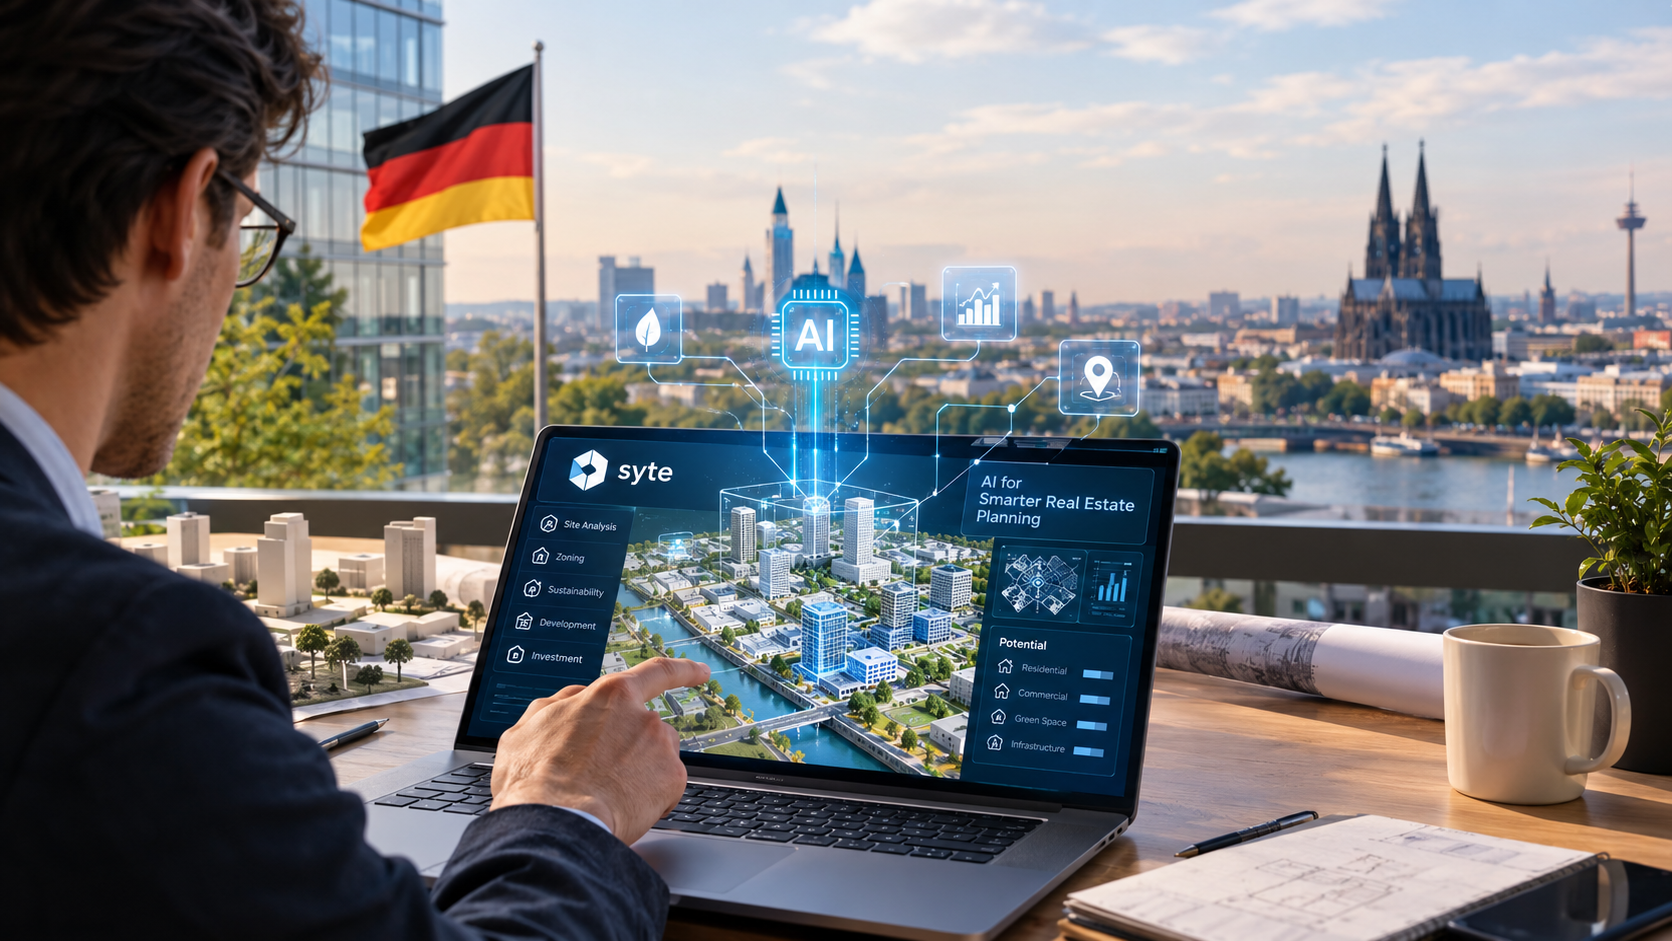
Real estate development has traditionally depended on fragmented information. Developers, banks, architects and investors often need to evaluate land ownership, planning rules, zoning, building potential, renovation requirements, energy performance and economic feasibility before capital can be committed. German PropTech company syte is attempting to automate that process. The company announced in September 2026 that it had raised €9 million in a Series A funding round to expand its AI-powered land and real estate analytics platform across Europe.
The company combines large amounts of land and building data with proprietary artificial intelligence to evaluate what can potentially be built on a particular site, which legal and planning requirements may apply and whether a project could make economic sense. According to High-Tech Gründerfonds, the platform maps more than 62 million parcels in Germany and is already used by more than 200 customers for valuation, planning, investment analysis and portfolio assessment. The company says processes that can otherwise take weeks can be reduced to minutes.
The importance of the technology is easy to underestimate because it operates before construction begins. Yet the earliest stage of a property project is where enormous amounts of value can be created or destroyed. A developer that discovers late in the process that a site cannot support the intended building, that planning restrictions are more severe than expected or that renovation economics do not work may already have invested significant time and capital. Automating preliminary analysis can therefore change the economics of development even without changing the physical construction process.
The company is particularly interesting because its business model illustrates a broader shift in PropTech. Earlier generations of real estate software often focused on administration, listings, accounting or customer relationship management. The new generation is moving deeper into decision-making. AI is being used to answer questions such as: What can be built here? What might it cost? Which regulatory constraints apply? Which properties require renovation? Where are hidden development opportunities?
For institutional investors, this creates a potential competitive advantage. A large portfolio contains thousands or even millions of individual data points. Human teams cannot evaluate every parcel with the same depth. Machine-assisted analysis can instead identify a smaller set of properties that deserve human attention. The technology does not eliminate investment judgment; it changes where that judgment is applied.
syte’s €9 million financing is therefore less interesting as a startup funding headline than as a signal of where the real estate technology market is heading. The company says its recurring revenue doubled year-on-year and that it intends to expand beyond Germany into the wider European market.
The broader opportunity is the creation of a machine-readable real estate market. If every parcel, building, planning rule, energy characteristic and economic variable can be digitally represented and analyzed, investors can move from searching for properties to systematically discovering opportunities.
That transition is particularly relevant to the future of Aurivance. The next generation of real estate intelligence will not simply tell investors what happened. It will help them understand what could happen on a particular piece of land, in a particular building or across an entire portfolio. AI-powered property intelligence could ultimately become one of the most important layers between raw real estate data and investment decisions.

Sustainable Real Estate in 2026: A Ranking Reshuffle and What It Means for ESG-Focused Capital
Real estate’s sustainability leaderboard looks meaningfully different heading into the back half of 2026 than it did even twelve months ago — not because the sector’s underlying ESG commitments have weakened, but because the industry’s most-watched scorecard, the Corporate Knights Global 100 Most Sustainable Corporations ranking, overhauled its methodology this year in a way that has reshuffled the entire list, real estate included.
Why the Ranking Changed
The 2026 edition of the Global 100 introduced a new core metric called sustainable revenue momentum — how fast a company is growing the share of its revenue tied to sustainable activities — which now accounts for a full third of every company’s score, alongside overall sustainable revenues and sustainable investments. The effect was immediate and dramatic: Italian renewable energy producer ERG SpA, ranked just 18th a year earlier, jumped to first place in 2026, while Schneider Electric, last year’s top performer, fell all the way to 40th. Thirty-seven companies entered the ranking for the first time this year and 33 dropped off entirely — a level of turnover that Corporate Knights’ director of rankings, Michael Yow, has explicitly framed as a deliberate signal that speed of transition now matters as much as absolute sustainability performance. For real estate specifically, that shift rewards companies actively growing green-certified, energy-efficient and renewable-powered portfolios faster than peers, rather than simply companies that reached a high sustainability baseline years ago and have since plateaued.
City Developments Limited Remains the Sector’s Clearest Global 100 Representative
Amid that turnover, City Developments Limited (CDL) has held its position as Singapore’s — and one of the world’s — most consistently ranked sustainable real estate companies, landing at 69th place in the 2026 Global 100 and retaining its billing as Singapore’s top-ranked real estate and leasing company on the index. That continuity matters more this year than in past editions precisely because so many companies fell off the list entirely under the new momentum-weighted methodology; CDL’s survival reflects sustained, measurable progress rather than a one-time ESG initiative. The company’s net-zero-by-2030 operational target remains in place, built around continued emissions reductions since its 2017 baseline, an expanding solar footprint across its portfolio, and integration of low-carbon materials into new developments — with the added dimension in 2026 of leaning more heavily into smart-building and circular-economy design principles as differentiators in an increasingly crowded field of ESG-branded developers across Asia.
Prologis: Still a Sustainability Leader, But Not Necessarily on This Year’s List
Prologis remains one of the most closely watched names in sustainable logistics real estate, and 2026 has brought a fresh round of external recognition — the company was named to Fast Company’s 2026 World’s Most Innovative Companies list in the Urban Development & Real Estate category, to Fortune’s 2026 World’s Most Admired Companies list for a fifth consecutive year, and previously to TIME’s World’s Most Sustainable Companies list. Notably, though, Prologis’ own current list of sustainability accolades does not include a 2026 Global 100 placement, a departure from the company’s long run on that particular index through 2024. Whether that reflects the new momentum-weighted methodology penalizing an already-mature sustainability program, changes in how REITs are scored this cycle, or simply a normal year-to-year fluctuation in a list that saw a third of its constituents turn over, is not fully clear from public disclosures — but it is a reminder that even best-in-class ESG performers are not guaranteed permanent placement on a ranking that has explicitly redesigned itself to reward acceleration over accumulated achievement. On substance, Prologis’ underlying sustainability program continues largely unchanged: net-zero logistics facility targets, extensive green bond financing, and continued build-out of on-site solar and renewable power procurement across its global industrial portfolio remain core to its investor pitch regardless of any single index placement.
CapitaLand and the Broader Asia-Pacific Field
CapitaLand Investment continues to pursue its carbon-neutrality-by-2050 target with an interim 46 percent reduction goal by 2030, and remains active across green-certified commercial and retail development in Singapore and the broader region. Corporate Knights has separately begun publishing more granular regional rankings alongside the flagship Global 100 — including a newly expanded Asia Pacific 50 Most Sustainable Corporations list — which gives investors a more localized view of how Asia-Pacific real estate players are performing relative to regional peers rather than only against global industrial giants, a useful lens given how differently sustainability regulation and green-financing incentives are structured across Singapore, mainland China and the rest of the region.
Digital Realty and the Data Center Real Estate Wrinkle
Digital Realty’s sustainability profile has become more consequential in 2026 precisely because data center real estate has become one of the fastest-growing property types globally, driven by AI infrastructure buildout. With a market capitalization now above $54 billion, Digital Realty’s continued commitment to 100 percent renewable-powered facilities and LEED certification targets places it at the center of a genuinely new tension in real estate ESG: data centers are simultaneously among the most energy-intensive property types to operate and among the most capital-intensive to build, meaning their sustainability credentials now carry outsized weight in how the broader real estate sector’s carbon footprint is perceived by regulators and institutional allocators alike.
European Regulation Continues to Tighten the Baseline
The regulatory backdrop that made ESG “a strategic imperative” in 2025 has, if anything, hardened further in 2026. The European Union’s target of a 55 percent reduction in emissions by 2030 remains the binding baseline against which EU-exposed real estate portfolios are measured, and companies like Inmobiliaria Colonial continue to integrate green certifications and energy-efficient retrofits into their office portfolios specifically to stay ahead of that regulatory curve rather than simply to capture a marketing advantage. For institutional investors, this increasingly means that ESG compliance in European real estate has shifted from a differentiator to a baseline license to operate — non-compliant office stock risks accelerated obsolescence as green-certified space commands both rent premiums and lower vacancy.
What This Means for Elite and Institutional Investors
The core takeaway for 2026 is not that sustainability has become less important in real estate — every indicator suggests the opposite, with green-certified assets continuing to command higher rents and lower vacancy than uncertified comparables. Rather, the lesson is that the scorecards investors have relied on to identify sustainability leaders are themselves evolving quickly, and a company’s historical ranking is no longer a reliable proxy for current performance. Corporate Knights’ pivot toward rewarding momentum over accumulated achievement means investors evaluating real estate companies on ESG credentials in 2026 should weight the trajectory of a company’s green revenue and green financing activity at least as heavily as its absolute certifications and legacy rankings — a more dynamic, and considerably more demanding, standard than the one that defined the 2019 Global 100 cohort this note originally tracked.


