

Business
Global Success Stories in Luxury Hospitality: Real Estate and Exclusivity


Introduction
Luxury hospitality has evolved into a model that combines brand prestige, strategic locations, and exclusive services with high-value real estate investments. Iconic figures such as Robert De Niro, Giorgio Armani, and Lionel Messi, alongside renowned brands like Bulgari and The Ritz-Carlton, have created hotel chains that serve as both profitable real estate assets and exceptional hospitality experiences. This article analyzes five success stories—Nobu Hotels, Armani Hotels, Bulgari Hotels, The Ritz-Carlton, and MiM Hotels—highlighting their business models centered on luxury real estate, exclusive services, investment values, and projected profits, positioning them as benchmarks in the global luxury market.
Success Stories in Luxury Hospitality
1. Nobu Hotels: Gastronomy and Global Luxury
Location: 17 properties in 2025, including Miami Beach, London, Barcelona, Tokyo, and Muscat (Oman), with planned openings in Lisbon, Manchester, and Abu Dhabi (PR Newswire, 2023).
Real Estate Value and Profits: Launched in 2013, Nobu Hotels’ portfolio is valued at over $500 million, with properties like Nobu Miami Beach, acquired for $20 million and renovated (Forbes, 2022). Rates range from $300-$500 per night, with 85% occupancy in London (Nobu Hotels, 2023). Branded residences in Muscat fetch $1-$3 million per unit, generating additional revenue (PR Newswire, 2023). Estimated annual returns are 10-12%, per partners like Enevoria Development.
Business Model: Nobu leverages the fame of Robert De Niro and chef Nobu Matsuhisa with elite gastronomy, attracting a global clientele (CNN, 2022). Dynamic destinations (Shoreditch, Yiti Beach) ensure high demand, while residences diversify income. Sustainability, with LEED certifications in several properties, strengthens the brand (Nobu Hotels, 2023).
Design and Exclusive Services: Hotels blend Japanese minimalism with local touches, offering suites with private terraces and ocean views. Amenities include Nobu restaurants, high-end spas, and rooftop bars (e.g., Barcelona). Personalized packages, like omakase dinners, appeal to affluent guests (Tripadvisor, 2024).

Real Estate Strategy: Nobu invests in high-value markets, optimizing revenue through premium rates and residences. Expansion into secondary destinations like Lisbon ensures long-term growth.
Sources:
-
Nobu Hotels (www.nobuhotels.com, 2023).
-
PR Newswire, “Nobu Hotel and Residences Muscat Announced” (2023).
-
CNN, “Luxury Hotels by Celebrities” (2022).
-
Forbes, “Nobu’s Expansion Strategy” (2022).
-
Tripadvisor, Nobu Hotel reviews (2024).
2. Armani Hotels: Minimalist Sophistication
Location: Dubai (Burj Khalifa), Milan, with planned expansions in New York, Paris, and Diriyah (Saudi Arabia, 2026) (Armani Hotels, 2023).
Real Estate Value and Profits: The Armani Hotel Dubai, opened in 2010, required a $100 million investment, with a current value of $150-$200 million (Emaar Properties, 2022). The Milan hotel adds $100 million to the portfolio (Forbes, 2023). Rates of $700-$1,000 per night and 75-80% occupancy generate 8-10% annual returns (Emaar Properties, 2023).
Business Model: Armani Hotels uses Giorgio Armani’s minimalist aesthetic to attract an elite clientele, with properties of 95-160 rooms (CNN, 2022). Collaboration with Emaar Properties ensures efficient management, while Armani Casa’s design elevates perceived value. Expansion into Saudi Arabia targets Middle Eastern luxury tourism (Armani Hotels, 2023).
Design and Exclusive Services: Interiors feature neutral tones, marble, and smart home technology, with Dubai suites offering Gulf views. Amenities include Armani/Spa, Michelin-starred restaurants (Milan), and bars overlooking the Dubai Fountain. Armani boutiques add exclusivity (Tripadvisor, 2024).
Real Estate Strategy: Iconic locations (Burj Khalifa, Milan’s fashion district) ensure high demand and appreciation. Sustainable design, with recycled materials in Milan, maximizes profitability (Armani Hotels, 2023).
Sources:
-
Armani Hotels (locations.armani.com, 2023).
-
Emaar Properties, Annual Report (2022, 2023).
-
Forbes, “Armani’s Luxury Ventures” (2023).
-
CNN, “Luxury Hotels by Designers” (2022).
-
Tripadvisor, Armani Hotel Dubai reviews (2024).
3. Bulgari Hotels & Resorts: Jewelry-Inspired Luxury
Location: 9 properties in 2025, in Milan, London, Dubai, Paris, Beijing, Tokyo, Bali, Rome, and Shanghai, with planned openings in Los Angeles and Miami (2026) (Bulgari Hotels, 2023).
Real Estate Value and Profits: The portfolio exceeds $1 billion, with properties like Bulgari Hotel Dubai ($150 million) and Bulgari Hotel Rome (renovated historic building) (El Mundo, 2023). Rates of $900-$1,500 per night and 80-90% occupancy yield 10-12% returns (Marriott International, 2023). Branded residences in Dubai reach $5 million per unit (Bulgari Hotels, 2023).
Business Model: Bulgari combines its jewelry heritage with boutique hospitality (76-100 rooms), partnering with Marriott International for efficient management (CNN, 2022). Residences diversify income, while sustainability (eco-friendly materials) bolsters the brand (Bulgari Hotels, 2023).
Design and Exclusive Services: Interiors feature Italian marble, silks, and jewel-inspired details, as in Bulgari Hotel Paris with Champs-Élysées views. Amenities include luxury spas, Michelin-starred restaurants (Il Ristorante – Niko Romito), and Bulgari boutiques (Tripadvisor, 2024).
Real Estate Strategy: Bulgari invests in luxury districts (Knightsbridge, Piazza Augusto Imperatore), ensuring appreciation. Residences and Marriott’s management optimize portfolio value.
Sources:
-
Bulgari Hotels (www.bulgarihotels.com, 2023).
-
El Mundo, “Bulgari Hotel Rome Opens” (2023).
-
Marriott International, Investor Relations (2023).
-
CNN, “Luxury Brand Hotels” (2022).
-
Tripadvisor, Bulgari Hotel reviews (2024).
4. The Ritz-Carlton: Classic Hospitality Excellence
Location: Over 100 properties in 2025, including New York, Paris, Hong Kong, Dubai, and Singapore, with expansions in Melbourne and Riyadh (Marriott International, 2024).
Real Estate Value and Profits: Owned by Marriott International, The Ritz-Carlton’s portfolio is valued at over $5 billion, with properties like The Ritz-Carlton Dubai ($200 million) (Forbes, 2023). Rates of $600-$1,200 per night and 80% occupancy generate 9-11% returns (Marriott International, 2023). Branded residences in Miami fetch $2-$10 million per unit (The Ritz-Carlton, 2023).
Business Model: The Ritz-Carlton focuses on classic luxury hospitality, with 100-300-room properties blending tradition and modernity. Marriott’s management ensures consistency, while residences and exclusive clubs diversify income. Sustainability, with LEED certifications in Hong Kong, attracts modern travelers (The Ritz-Carlton, 2023).
Design and Exclusive Services: Interiors combine classic elegance with contemporary touches, as in The Ritz-Carlton Paris with chandeliers and marble. Amenities include luxury spas, award-winning restaurants (IDAM by Alain Ducasse in Doha), and panoramic bars (Tripadvisor, 2024).
Real Estate Strategy: Premium locations (Manhattan, Marina Bay) ensure high demand and appreciation. Residences and professional management maximize profitability, with expansions into emerging markets like Saudi Arabia.
Sources:
-
The Ritz-Carlton (www.ritzcarlton.com, 2023).
-
Marriott International, Investor Reports (2023, 2024).
-
Forbes, “Ritz-Carlton’s Global Reach” (2023).
-
Tripadvisor, Ritz-Carlton reviews (2024).
5. MiM Hotels: Lionel Messi’s Real Estate Empire
Location: Six properties in Spain (Sitges, Ibiza, Mallorca, Baqueira, Sotogrande) and Andorra (Escaldes-Engordany) (MiM Hotels, 2023).
Real Estate Value and Profits: Since 2017, MiM Hotels, in partnership with Majestic Hotel Group, has built a portfolio valued at over $100 million, integrated into the Edificio Rostower Socimi REIT (€223 million in 2025) (Expansión, 2023). Properties like MiM Sitges (€30 million, 2017) and MiM Baqueira (€26 million, 2021) reflect investments in premium destinations (Forbes, 2024). Rates of €220-€260 per night in Sitges, with 80% occupancy, generate stable income (MiM Hotels, 2023). The REIT offers tax advantages (0% taxation in Spain under certain conditions), with 8-10% annual returns (Expansión, 2023).
Business Model: MiM Hotels leverages Lionel Messi’s fame to attract an elite clientele, with boutique properties of 31-141 rooms. Geographic diversification (coast, mountain, urban) and sustainability (LEED Platinum certification in Sitges) are core pillars (MiM Hotels, 2023). Majestic’s management allows Messi to focus on expansion, with rumored projects in the Caribbean (Forbes, 2024).
Design and Exclusive Services: Each hotel reflects its locale: Art Deco in MiM Ibiza, Scandinavian minimalism in MiM Andorra, alpine style in MiM Baqueira. Amenities include hydrotherapy spas, rooftop bars (Sky Bar in Sitges), and the Leo Messi Suite in Andorra for personalized luxury. Gourmet restaurants and eco-conscious services attract luxury travelers (Tripadvisor, 2024).
Real Estate Strategy: Diversification reduces risk, while premium locations ensure appreciation. Targeting adult (Ibiza, Mallorca) and family (Baqueira) markets captures diverse segments. The REIT optimizes liquidity and tax efficiency.
Sources:
-
MiM Hotels (www.mimhotels.com, 2023).
-
Expansión, “Messi’s REIT Socimi” (2023).
-
Forbes, “Lionel Messi’s Real Estate Empire” (2024).
-
Tripadvisor, MiM Hotels reviews (2024).
Real Estate Strategy: Keys to Success
These cases highlight strategies that maximize value and profitability:
-
Premium Locations: From Burj Khalifa (Armani) to Ibiza (MiM), locations ensure high demand and appreciation.
-
Diversification: Portfolios spanning urban, coastal, and cultural destinations reduce risk.
-
Sustainability: LEED certifications (MiM Sitges, Nobu, Ritz-Carlton) and eco-friendly materials (Bulgari) enhance value.
-
Tax Efficiency: Structures like REITs (MiM) and partnerships with Marriott (Bulgari, Ritz-Carlton) or Emaar (Armani) optimize returns.
-
Brand and Exclusivity: The fame of Messi, De Niro, Armani, and brands like Bulgari and Ritz-Carlton drives premium rates.
-
Diversified Revenue: Restaurants, spas, and branded residences generate additional cash flows.
Comfort and Luxury: The Guest Experience
The hotels prioritize exclusive experiences:
-
Boutique Scale: Properties with 31-300 rooms ensure personalized service.
-
Unique Design: From MiM Ibiza’s Art Deco to Ritz-Carlton’s classic elegance, design reflects brand identity.
-
Premium Amenities: Spas, award-winning restaurants, and rooftop bars elevate the experience.
-
Sustainability: Eco-conscious products and energy-efficient systems appeal to modern travelers.
Market Impact and Future Outlook
These portfolios, valued in hundreds or billions, lead the luxury market. With luxury tourism projected to grow at a 7.9% CAGR through 2030 (Statista, 2023), the brands are poised for expansion: Nobu to Lisbon, Armani to Diriyah, Bulgari to Miami, Ritz-Carlton to Riyadh, and MiM to the Caribbean. Their success blends high-value real estate with exclusive experiences.
Conclusion
Nobu Hotels, Armani Hotels, Bulgari Hotels, The Ritz-Carlton, and MiM Hotels demonstrate how brand or iconic figure prestige can transform into hospitality empires that combine luxury, exclusivity, and real estate profitability. With strategic locations, personalized design, and robust financial strategies, these cases set a standard in the industry, generating valuable assets and unforgettable experiences for a global elite clientele.
Additional Source:
-
Statista, “Luxury Travel Market Forecast” (2023).

The most attractive real estate business models in 2026 continue to be shaped by the same three forces that reordered the industry after 2023: automation, capital scarcity in emerging markets, and a widening gap between prime and secondary product. For elite and high-net-worth investors, the opportunity set has narrowed slightly compared to 2025 — several crowdfunding platforms have faced tighter regulatory scrutiny, while logistics and luxury development have consolidated their position as the two clearest outperformers. Below is an updated read on where sophisticated capital is actually going.
1. Property Management Franchises
Property management franchises remain a low-volatility way to hold real estate exposure without direct operating risk, and the model has held up well through 2026’s higher-for-longer rate environment in the US. Franchise networks such as Real Property Management and Property Management Inc. continue to expand in metropolitan markets with structurally tight rental supply, offering investors predictable fee-based income tied to assets under management rather than to price appreciation — a distinction that has become more valuable as US home-price growth has essentially flattened this year, with the national median home value sitting near $360,000 and just 0.2 percent year-over-year growth. For elite investors, the appeal has not changed: a proven operating system, ongoing franchisor support, and a revenue base that holds up even when transaction volumes slow, since rental demand and property-management fees are far less cyclical than sales commissions.
2. Digital Investment Platforms (Real Estate Crowdfunding)
Real estate crowdfunding in Latin America has matured considerably since 2025, though not without turbulence. In Mexico, Briq.mx has continued operating under the country’s Fintech Law, but its own leadership has been vocal in 2026 about a structural disadvantage: unlike banks and regulated savings institutions, crowdfunding platforms do not benefit from the same tax incentives, which their executives argue discourages broader retail participation even though regulatory supervision itself is strict. 100 Ladrillos, based in Guadalajara, has continued to grow its footprint — now employing more than 100 people — and has increasingly positioned itself around nearshoring-driven industrial and logistics assets rather than purely residential product, a pivot that mirrors where institutional capital has also been moving. In Argentina, the sector has diversified beyond the original crowdfunding pioneers toward platforms like Bricksave, which reported financing 323 properties for its investor base in the first quarter of 2026 alone, with 269 units currently under management across six US cities — reflecting a broader trend of Argentine investors using crowdfunding platforms to access dollarized US residential assets rather than only local Argentine projects, a hedge against peso volatility that has become increasingly common among the country’s savers. The regulatory environment is also tightening: Argentina’s securities regulator, the CNV, has stepped up its scrutiny of real estate crowdfunding structures, a trend elite investors should watch closely given how the category is classified will determine investor protections going forward.
3. Development of Luxury and Premium Properties
Luxury development remains one of the clearest wealth-preservation plays available to elite investors, and Puerto Madero continues to anchor that thesis in Argentina. The neighborhood closed 2025 as the most expensive in Buenos Aires, with average values around US$6,144 per square meter — a premium that has held despite Argentina’s broader macroeconomic volatility, precisely because Puerto Madero functions less as a conventional residential market and more as a dollarized store of value for Argentine capital seeking safety within the country’s own borders. That said, the investment case has grown more nuanced this year: independent market analysis increasingly flags that Puerto Madero’s rental yields remain low relative to its purchase prices, and that the neighborhood’s appeal is now concentrated almost entirely among Argentine buyers seeking capital preservation rather than international investors chasing yield, a distinction elite allocators should weigh carefully before assuming Puerto Madero behaves like a global luxury market such as Manhattan. In the US, the luxury development pipeline led by firms like Related Companies, SL Green Realty and Extell Development continues to benefit from persistent scarcity of premium inventory in gateway cities, though 2026 has brought a more selective buyer, with elevated financing costs continuing to separate well-capitalized developers from those reliant on leverage.
4. Technological Solutions for Real Estate (PropTech)
PropTech platforms have scaled meaningfully since 2025. Zillow now draws well over 200 million monthly visitors — more than five times the figure commonly cited just a year ago — and has continued expanding its AI-driven agent tools and a broadened listing partnership with Realtor.com launched in May 2026, even as the company has faced regulatory friction this year, including an antitrust suit alongside Redfin over alleged rental-market competition suppression, and a brief, court-reversed loss of access to Chicago-area listings. For sellers looking to cut commission costs, flat-fee platforms like Houzeo have become considerably more relevant in 2026: with the average US agent commission now running around 5.7 percent of sale price according to a 2026 industry survey — notably higher than immediately after the 2024 NAR settlement that was supposed to compress commissions — a seller listing a roughly $418,000 home through a traditional agent pays close to $23,800 at closing, compared to roughly $2,300 through a flat-fee platform like Houzeo. For elite investors managing larger residential or small multifamily portfolios, this commission gap is increasingly material to net returns, particularly on more liquid, frequently-traded assets.
5. Investments in Industrial and Logistic Properties
Industrial and logistics real estate remains the standout performer in the Argentine market heading into 2026. According to ARLOG’s annual industry survey of more than 500 logistics professionals, 83 percent of logistics companies plan to invest in 2026, with 79 percent of that capital directed toward warehouse technology, robotics, automation and security systems, and 70 percent planning to expand physical warehouse capacity outright. Premium industrial vacancy in the Buenos Aires metropolitan area has stayed tight, sitting near 8.96 percent as of mid-2026, supporting continued rent growth in the sector’s best-located assets. The broader macro backdrop reinforces the thesis: Argentina’s RIGI investment incentive regime has already attracted more than US$150 billion in announced, evaluated or approved long-term infrastructure projects, concentrated in provinces including Neuquén, Río Negro, San Juan, Jujuy, Salta and Mendoza, a wave of capital that is expected to generate meaningful downstream demand for logistics and industrial real estate as these regions develop into genuine industrial poles over the coming years. For elite investors, industrial and logistics assets continue to offer the combination that luxury residential often cannot: genuine yield, tied to structural demand drivers like nearshoring and infrastructure investment, rather than purely capital-preservation logic.
6. Sustainable Real Estate and Smart Homes
Sustainability and smart-home integration have moved from differentiator to baseline expectation in premium developments throughout 2026, particularly as ESG-oriented institutional capital increasingly treats green-building certification as a genuine underwriting criterion rather than a marketing feature. Keyless entry, integrated energy management and building-wide automation continue to expand across the premium residential and short-term rental segments, following the model pioneered by operators like Casai, and developers are increasingly bundling these features into new luxury construction from the outset rather than retrofitting them. The elite continues to place a premium on these attributes not purely for environmental reasons but because they measurably reduce operating costs and improve asset liquidity at resale — a dynamic that has become more pronounced as buyers in mature luxury markets increasingly factor sustainability credentials into valuation.
Critical Reflection
The risks flagged in 2025 remain just as relevant heading into 2026, and in some cases have sharpened. Real estate crowdfunding continues to face genuine regulatory uncertainty across Latin America — Mexico’s tax-treatment disadvantage and Argentina’s tightening CNV scrutiny both suggest the sector’s rules are still being written, which should temper allocation size for elite investors until the regulatory picture stabilizes. Luxury markets like Puerto Madero remain vulnerable to the gap between headline pricing and actual liquidity — high average values do not guarantee the ability to exit a position quickly, and yields in these markets remain structurally low compared to income-generating alternatives. PropTech adoption, while accelerating, continues to face legal and structural friction, as this year’s antitrust litigation against Zillow and Redfin illustrates — platform dominance itself is now drawing regulatory attention in ways that could reshape how commissions and listing access work industry-wide. The clearest through-line from 2025 to 2026 is that industrial and logistics real estate, backed by measurable demand drivers like nearshoring and infrastructure spending, continues to offer a more defensible risk-adjusted case than pure capital-preservation plays in luxury residential — a distinction elite investors should weigh more heavily than headline prestige when allocating fresh capital this year.
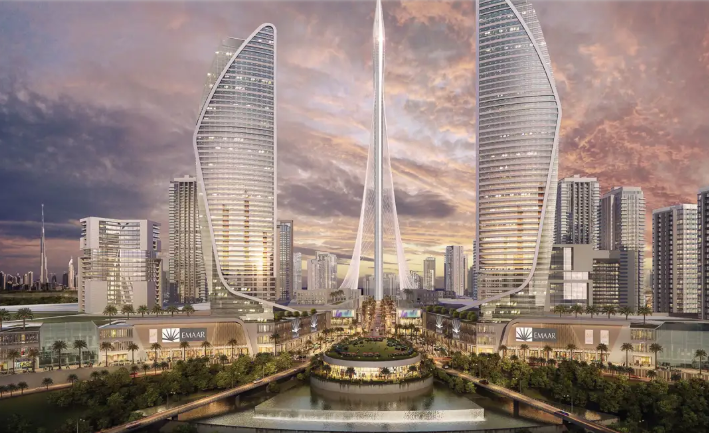
Investing in the World’s Tallest Buildings: The 2026 Playbook for Supertall Real Estate
Real estate tied to the world’s tallest buildings continues to sit in a category of its own. These towers are not simply large buildings — they are engineered scarcity, occupying irreplaceable positions in global financial hubs, commanding tenant and buyer premiums that ordinary Grade-A stock cannot match, and generating income from far more than rent alone. As of September 2026, the five tallest completed buildings on Earth, ranked by the Council on Tall Buildings and Urban Habitat, are Burj Khalifa in Dubai, Merdeka 118 in Kuala Lumpur, Shanghai Tower, the Makkah Royal Clock Tower in Saudi Arabia, and the Ping An Finance Centre in Shenzhen. Together they offer a useful cross-section of how supertall real estate actually performs as an investment class — and where the risks sit.
Burj Khalifa, Dubai, UAE — 828 meters, 163 floors
Burj Khalifa has held the title of world’s tallest building since 2010 and, at 828 meters, still leads its nearest rival by close to 150 meters — a margin that has remained essentially unchallenged for fifteen years. Developed by Emaar Properties, the tower is a mixed-use asset combining luxury residences, corporate offices, the Armani Hotel and extensive retail, with residential units historically transacting at premium pricing in Dubai’s ultra-prime segment. The investment case rests less on any single income line than on the combination: residential sales and rentals, office leasing, hotel operations, and one of the highest-grossing observation decks in the world, all under one address whose brand value alone commands a premium over otherwise comparable Downtown Dubai product. Emaar itself remains one of the most closely watched developers globally — the company’s chairman confirmed this year that Dubai hotel occupancy has recovered to around 60 percent after dipping sharply during regional conflict, and Emaar is preparing a roughly $55 billion urban development for once conditions stabilize further, underscoring the scale of capital still committed to the emirate’s built environment.
Merdeka 118, Kuala Lumpur, Malaysia — 678.9 meters, 118 floors
Completed in 2023 and developed by state-linked investment fund Permodalan Nasional Berhad, Merdeka 118 is the world’s second-tallest building and the tallest in Southeast Asia. The tower combines offices, a Park Hyatt hotel, retail and residential space in Kuala Lumpur’s financial district, and its sustainability credentials — energy-efficient systems designed to meet international green-building standards — have made it a reference point for ESG-oriented institutional capital looking at Southeast Asian office exposure. For multinational tenants seeking a single prestige address in Kuala Lumpur, Merdeka 118 functions similarly to how Petronas Towers did a generation earlier: an anchor asset whose scarcity value supports premium rents even as broader Kuala Lumpur office stock faces more competitive, oversupplied conditions.
Shanghai Tower, Shanghai, China — 632 meters, 128 floors
Shanghai Tower, the world’s tallest twisting skyscraper, anchors Shanghai’s Lujiazui financial district alongside the Shanghai World Financial Center and Jin Mao Tower, forming one of the most concentrated clusters of supertall office space anywhere on Earth. Owned and operated by Shanghai Tower Construction & Development, the building combines Grade-A offices, a Jin Jiang-operated luxury hotel, retail and one of the world’s highest observation decks. Its investment profile is distinct from the Gulf and Southeast Asian towers on this list in one important respect: as a state-linked asset in a market where foreign direct ownership of trophy office towers is tightly controlled, exposure for international investors typically comes indirectly, through listed developers, REIT-like vehicles, or joint-venture leasing arrangements with multinational tenants, rather than through direct equity ownership of the tower itself.
Makkah Royal Clock Tower, Mecca, Saudi Arabia — 601 meters, 120 floors
The Makkah Royal Clock Tower is the tallest hotel building in the world and the anchor of the Abraj Al-Bait complex overlooking the Masjid al-Haram, the holiest site in Islam. Its investment profile is unlike any other building on this list: demand is driven not by corporate tenancy or luxury residential appeal but by religious pilgrimage, with the Hajj and Umrah seasons generating extraordinarily high and highly predictable occupancy for the Fairmont-operated hotel component. Saudi Arabia’s broader push to expand religious tourism capacity — alongside the kingdom’s parallel real estate opening measures, including its newly operational foreign property ownership framework and the Public Investment Fund’s coastal development pipeline — makes Mecca’s hospitality-anchored supertall real estate one of the more insulated income profiles in this category, largely uncorrelated with the global office and luxury residential cycles that drive the other towers on this list.
Ping An Finance Centre, Shenzhen, China — 599.1 meters, 115 floors
Built as the headquarters for Ping An Insurance, China’s second-largest insurer, the Ping An Finance Centre anchors Shenzhen’s Futian central business district and is directly integrated with the city’s metro network and the Guangzhou–Shenzhen–Hong Kong high-speed rail link — a degree of transit integration that is itself a meaningful driver of long-term tenant demand in a city that has grown to nearly 13 million people since its designation as a Special Economic Zone. More than 100 floors of office space, occupied principally by Ping An and its financial-services subsidiaries, sit above a retail podium and conference facilities, with a public observation deck and private club occupying the pyramidal crown. As with Shanghai Tower, direct foreign equity access is limited; the more realistic route for outside investors is indirect, through listed Chinese financial and property vehicles or leasing relationships, rather than acquiring a stake in the tower itself.
Why Supertall Real Estate Behaves Differently From Ordinary Prime Assets
Several structural features distinguish these buildings from conventional trophy office or residential towers, and they explain why supertall assets have historically commanded a premium even through real estate downturns. First is brand value: a Burj Khalifa or Merdeka 118 address functions as a marketing asset in its own right for corporate tenants and luxury buyers, which supports occupancy and pricing power independent of local market softness. Second is revenue diversification — nearly every building on this list blends office, hospitality, residential and tourism income streams under a single roof, which cushions the asset against a downturn in any single sector in a way a pure-play office tower cannot replicate. Third, and increasingly relevant to ESG-focused institutional capital, is sustainability positioning: newer entrants to the supertall category, Merdeka 118 chief among them, have been designed from the outset to meet international green-building certification standards, a factor that is becoming a genuine underwriting criterion rather than a marketing footnote for large allocators.
The Access Problem — and Where Tokenization Genuinely Fits
The single biggest constraint on investing in this category is access. These are, almost without exception, either sovereign-linked, state-owned or closely held corporate assets, meaning direct equity ownership is simply not available to most investors, institutional or individual. That access gap is precisely why real estate tokenization has drawn serious institutional attention over the past two years — not as a retail gimmick, but as a genuine mechanism for fractionalizing ownership of otherwise inaccessible trophy assets. Dubai’s Land Department, working with the Virtual Assets Regulatory Authority and the Central Bank of the UAE, has already launched a pilot phase of blockchain-based real estate tokenization specifically framed around expanding fractional ownership and international participation in the emirate’s property market. Academic and regulatory frameworks published this year have likewise moved tokenization from experimental blockchain use case toward regulated market infrastructure, emphasizing that the technology is best understood as augmenting existing ownership and regulatory structures rather than replacing them.
For investors specifically interested in supertall and trophy real estate, the realistic paths to exposure today remain listed developer equity — Emaar Properties for Dubai exposure, PNB-linked vehicles for Merdeka 118, listed Chinese property and insurance names for Shanghai Tower and Ping An Finance Centre — alongside REITs holding comparable trophy assets, and a still-nascent but regulator-backed tokenization market that is worth monitoring closely rather than entering on the basis of any single platform’s marketing claims. As with any emerging asset-access mechanism, the platforms offering fractional or tokenized exposure vary enormously in regulatory standing, custody arrangements and transparency, and warrant the same due diligence an investor would apply to any unlisted vehicle — verified regulatory registration, clear custody of the underlying asset, and an audited link between the token and actual title or economic rights, rather than marketing promises of low minimums and instant liquidity.
The Bottom Line
Supertall buildings remain among the most resilient trophy assets in global real estate precisely because so little new competing supply can realistically be built — each of the towers above required years of specialized engineering, extraordinary capital outlay and, in several cases, direct government or sovereign backing to complete. That scarcity is the entire investment thesis. The risk for investors is less about the buildings themselves and more about the access route chosen to reach them: direct ownership is largely closed, indirect listed exposure carries the operating and governance risk of the parent developer or state entity, and the tokenization route, while increasingly credible where regulators like Dubai’s are directly involved, still requires far more scrutiny of the platform than of the underlying asset.
Asia-Pacific’s luxury property market is undergoing a geographic broadening that is beginning to reshape where the region’s wealthiest buyers and family offices concentrate their capital. For years, luxury real estate investment in the region clustered predictably around a handful of established hubs — Hong Kong, Singapore, Tokyo and Sydney chief among them. That pattern is loosening. Branded residences are expanding into a wider set of markets, new destinations are drawing sustained attention from international buyers for the first time, and family-office capital — increasingly the dominant force in the region’s hospitality sector — is following that expansion rather than confining itself to the traditional wealth capitals.
The forum circuit tracking this shift makes the trend visible in real time. IHIF Asia, held in Hong Kong in September and drawing more than 500 senior hospitality investors, owners and developers, dedicated significant programming to exactly this dynamic — capital flows, asset repricing, private credit and cross-border investment trends spanning Japan, Southeast Asia, Greater China and a widening set of emerging markets across the region. That agenda mirrors a parallel shift happening in the private wealth world: Campden Wealth’s Asia-Pacific Family Office & Investment Forum, one of the region’s most established closed-door gatherings for single-family offices and ultra-high-net-worth investors, has increasingly centered its discussions on how capital moves between Asia, the Middle East and the West, and on embedding real estate, infrastructure and alternative investments into multi-generational portfolio strategy rather than treating them as tactical allocations.
The Family Office Report 2026 for the APAC region, produced by Hospitality Investor, captures where that capital is actually landing — and the answer increasingly includes markets that would not have appeared on a family office’s shortlist five years ago. Serviced apartments, extended-stay product, branded residences and hybrid living concepts are drawing capital alongside traditional hotel assets, reflecting a buyer base that is thinking about real estate less as a single-purpose hospitality bet and more as a flexible platform that can capture multiple forms of demand — leisure travel, business travel, and increasingly, long-stay residents relocating within the region for work or lifestyle reasons.
Two forces are driving the broadening beyond the traditional hubs. The first is straightforward pricing logic: as Hong Kong, Singapore and Tokyo prime real estate has become more expensive and more competitively bid by institutional capital, family offices — which prize flexibility and are less constrained by index-hugging mandates — have simply followed better risk-adjusted returns into adjacent and emerging markets. The second is geopolitical. Regional tensions and fractured alliances are reshaping capital flows in ways that make single-hub concentration look increasingly risky to family offices managing multi-decade horizons, pushing many toward deliberate geographic diversification across Japan’s hospitality reset, Southeast Asia’s growth markets, and selective opportunities in Greater China.
For developers and operators positioning for this shift, the implication is that the next wave of Asia-Pacific luxury real estate capital will not arrive exclusively through the traditional channels of sovereign wealth funds and global private equity shops bidding on trophy towers in gateway cities. It will increasingly come from family offices moving with more speed, more flexibility and a genuine willingness to build first-mover positions in markets not yet fully discovered by institutional capital — a pattern that rewards operators and developers who can offer direct access and co-investment structures over those relying solely on traditional fund-raising channels. The risk, as with any early-mover thesis, is that some of these emerging destinations lack the depth of liquidity and exit options that make gateway-city luxury real estate a comparatively safer long-term hold — meaning the expanded opportunity set comes bundled with a genuine widening of the region’s risk spectrum as well.


